GBM5MGA Management Accounting Assignment Sample
Read this GBM5MGA assignment example to explore management accounting principles, cost control, budgeting techniques and business performance analysis.
- Introduction
- Overview of Management Accounting
- Task 1: Expense Classification and Categorisation
- Task 2: Report on Managing Accounting
- a) Background
- b) BEP Sales
- c) New BEP due to cost fluctuations
- d) Higher costs in sales and marketing lead to new BEP and MOS
- e) Recommendations for improvement should be made
- f) Summary
- Task 3: Proposal for Setting up a System for Budgetary Control
- a) Background and Cash Study Overview
- b) Outlining the flaws of existing systems and giving suggestions for improvement in Budgetary Control
- c) The Budgets and Additional Details
- d) Methods of Using a Budgetary Control Process
- e) Recommendations
- f) Summary
- Type Assignment
- Downloads564
- Pages14
- Words3446
Introduction
This whole section is dedicated to understanding the role of management accounting for the report. In this report, its objectives are met by focusing on each task, starting with the initial Task 1 that handles the classification and categorisation of expenses. In Task 2, it will explore management accounting, with break-even analysis being the central part. The third task is developing a better budget control system to solve the issues with those already in use.
Struggling with tight deadlines? Assignment Help For Students from Rapid Assignment Help UK delivers well-researched, expertly written papers on time, every time.
Overview of Management Accounting
The management accounting system handles data, goes over it and creates reports for the company. Some main aspects in accounting include making a budget, tracking costs, reviewing results, and anticipating the future. It underlines the importance of doing work accurately, quickly, relevantly and flexibly so that work, resources, and plans can be distributed equally to everyone.
Task 1: Expense Classification and Categorisation
a) Depreciation
 10 Years | MSc in Accounting
Depreciation is categorised as a fixed factory overhead, period and conversion cost. Since most businesses use straight line depreciation, it is more logical for them to see depreciation as a fixed cost. Changing the company’s manufacturing and production won't have an effect on depreciation under this method.
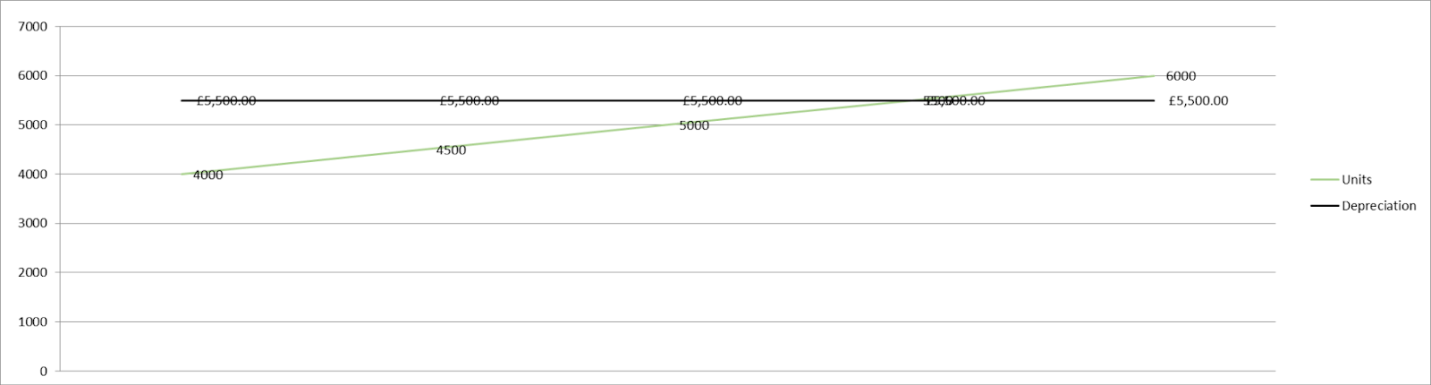
“Figure 1: Fixed Cost Depreciation”
b) Direct Material
Direct material is also called variable direct material, prime cost and conversion cost. As there are challenges in Metro Manufacturing’s inputs, changes in direct material cost per unit also follow the same pattern as direct labour.
c) Direct Labour
Direct labour consists of the variables, direct labour, prime and conversion cost. Since the direct labour cost per unit is up or down with the number of units made, it fits properly in the cost analysis (Asimakopulos, 2020).
d) Indirect Materials
For Metro Manufacturing, the company designates indirect materials as both variable and factory overheads costs. This is true because the costs at a factory vary with the amount of goods manufactured.
e) Machinery Rental
The equipment rented in Metro Manufacturing goes toward the fixed part of overhead and conversion costs. Renting machinery normally costs the same and is covered in the production process whenever raw materials are changed into finished goods.
f) Factory Utilities
Factory utilities belong to the variable costs, conversion costs and factory overhead group. This is due to the vital position these materials have in creating new products from raw goods (Thakur and Mogha, 2021).
g) Interest on Investments
Usually, interest costs in investment are considered fixed and period costs as they are always the same and happen for a certain period.
h) Storage Facility
The storage facility at Metro Manufacturing is an overhead cost since the main production happens inside the factory.
i) Shipping
Transportation is counted and is directly linked to the expense’s summary of Metro Manufacturing. It is because the cost of shipping changes a lot depending on how many units are shipped and these expenses are added to the raw materials cost for the company (Hirata, 2022).
j) Rent from Tenant
Most of the rent paid by tenants falls into the categories of fixed and period costs because it is charged the same amount each month or each year (Slater, 2020).
k) Supervisor Salary
In Metro Manufacturing, supervisors are given salaries that are considered a common cost for all business areas. According to Dibiku (2023), before any salaries are given, there are set terms and fixed amounts decided for employees and managers.
Task 2: Report on Managing Accounting
a) Background
This part explains management accounting in detail, with the focus being on break-even analysis. The report will show both the quantitative and qualitative results from before and after the equipment installation in its main section. One should focus on finding “BEP” by examining the real numbers from the performance section in the financial report. In the next steps of this study, it will present the “BEP”, with all the necessary details about changes in fixed and variable costs. The final stage of the analysis examines what will happen to the “BEP” if sales and marketing activities are expected to rise. The discoveries will shape the advice given, whereas with special emphasis on managing spending in later months and years.
b) BEP Sales
Get assistance from our PROFESSIONAL ASSIGNMENT WRITERS to receive 100% assured AI-free and high-quality documents on time, ensuring an A+ grade in all subjects.
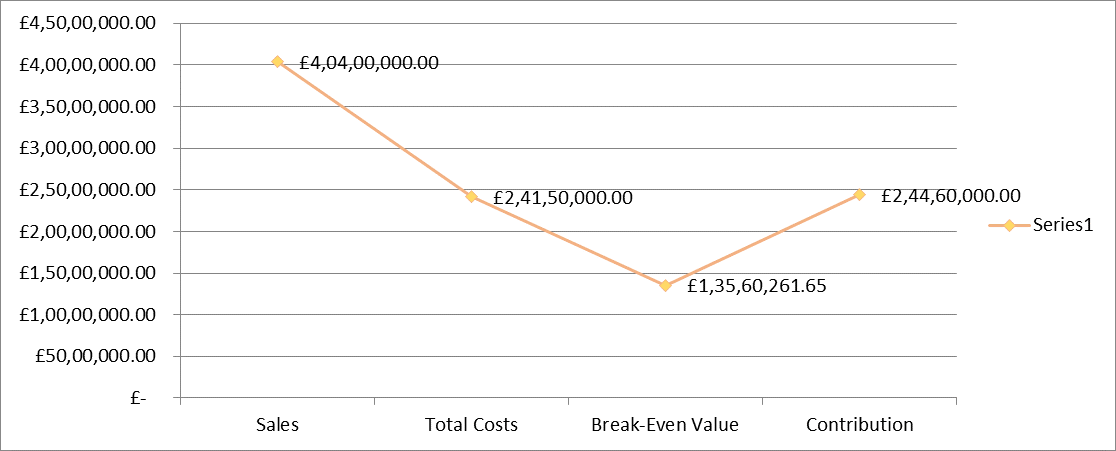
“Figure 2: Original BEP Level”
According to the data provided for “BEP” before the new equipment is introduced. “BEP” sales are calculated at GBP 13,560,261.56. The corresponding “BEP” units have been found to be 265.89 [Refer to Appendix 1]. All in all, the consumption shows that “BEP” units and their sales value do not reach the usual industry targets for Metro Manufacturing. As per statements and expressions of Bimayu (2023), having a low “BEP” is regarded as being helpful since it usually means the work can be completed more cost-effectively. The fact that Metro Manufacturing’s “BEP” is so low indicates that the total costs and revenues are equal only if production is kept low.
The “BEP” figure from the original level can be reached by calculating “fixed costs and contribution” divided by “contribution,” then multiplying it by overall revenue before any equipment is replaced. It is obvious from the diagram that the income from sales is the same as both “total cost” and “contribution,” yet the “total cost” is still much less than the sales revenue.
Vagner (2020) stated that using its resources wisely gives a company an advantage over others, as it helps cut costs and boost profits. As a result, it is evident from their pricing structure that Metro Manufacturing is making good profits, which allows managers to look for more ways to grow the business.
c) New BEP due to cost fluctuations
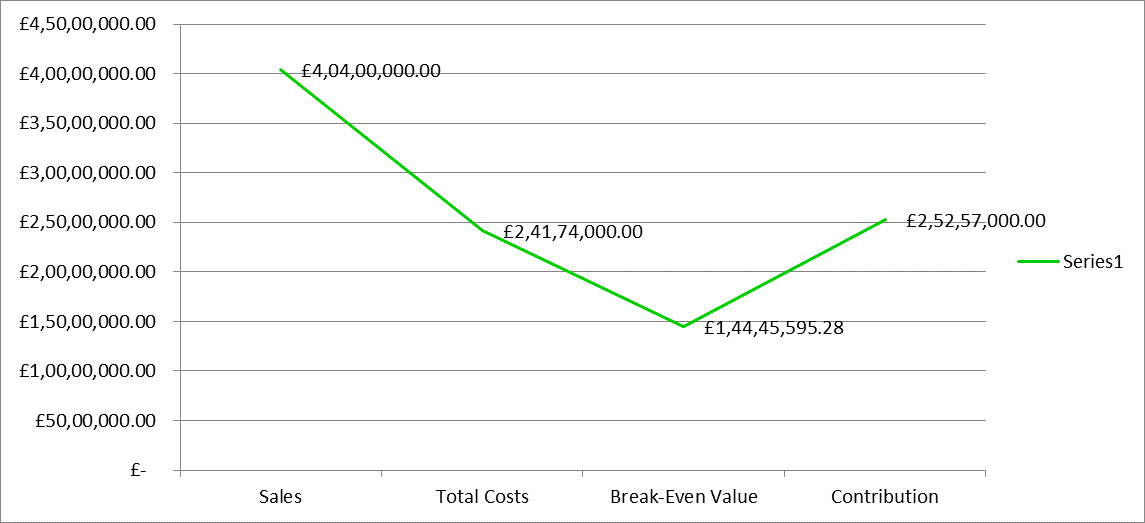
“Figure 3: Revised BEP due to fluctuations in costs”
Adding more equipment in the revised BEP results in a drop in variable costs by 5% and also leads to a rise in fixed costs by 10%. Being converted from BEP, the sales would be GBP 14,445,595.28, which is just slightly over the current sales from Metro Manufacturing. BEP unit value is now 285.43, which is higher compared to what was found in the earlier cost analysis [Refer to Appendix 2]. Jandaghian and Berardi (2020) critically stated and idealised that if the company has a higher BEP, it could face tough problems as it carries out its daily activities or in the long run. Therefore, the enhanced BEP caused by the new machinery might present some difficulties for Metro in the short term, whereas after a while, BEP is expected to reduce because the new machinery can do its job better. It appears from the graph that using the new machines did not lead to any changes in the total sales numbers. Still, the new figures indicate that the organisation spends GBP 24,174,000 and earns a contribution of GBP 25,257,000. So, only so much difference exists in the outcome: it happens because there are minor increases in overall costs, mainly because of the extra fixed costs the company pays due to higher production.
As per critical explanations and views of De Ridder (2024), When fixed costs increase over time (called incremental costs), companies find it hard to manage production in the first period. Rising fixed costs projected by the decision analysis model are the top drivers that led to BEP’s improved sales and unit growth, the report reveals. Should there be a rise in input costs, Metro might find itself facing problems that could reduce its profits in a short or long period, such as through lowering its profit margin.
d) Higher costs in sales and marketing lead to new BEP and MOS
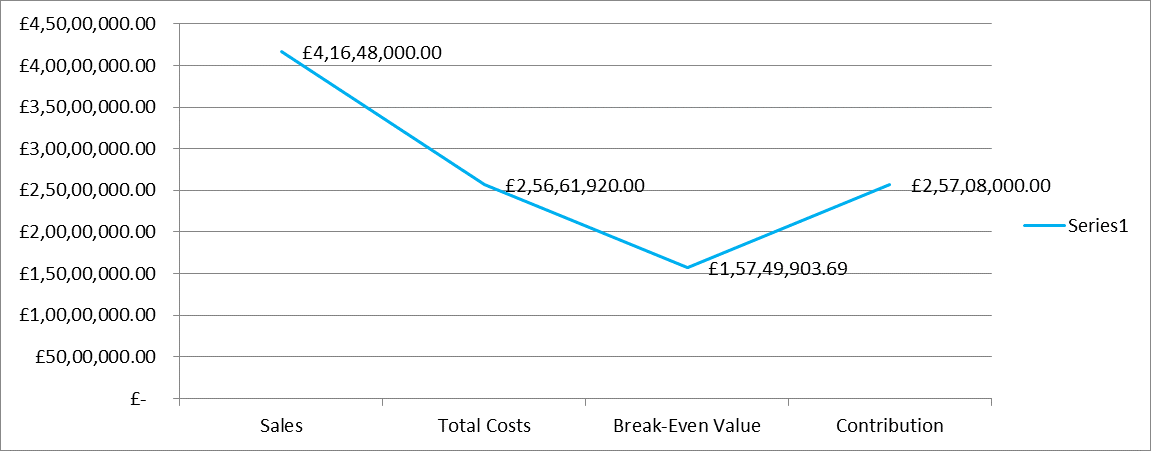
“Figure 4: Sales and marketing expenses changed, which led to a change in the BEP”
The illustrated chart of calculations covers the alternative BEP that takes into account higher marketing costs and more sales caused by Model 301. As a result of these calculations, BEP sales will come to GBP 15,749,903.69 and the number of BEP units will be 308.82. A score of 62.18% was determined for the additional measure, the MOS [See Appendix 3]. Because of this, it is easy to note that they are selling more and have a higher number of units in this scenario than in the ones before. A high BEP might mean that a company’s operations and production are not effective enough to help them grow in the future (Suzan, 2020). Even though Metro had hoped to get more sales of Model 301 by investing more in marketing, the company felt that attaining the extra BEP was no longer necessary after setting up the new equipment.
In the previous figure, one can see that “total sales” is 41,648,000, the total costs are 25,661,920 and the contribution is 25,708,000. As such, the difference with the first two is that while sales and contribution increased in this year, the costs that must be met are also higher. These changes in the total cost structure for Metro Manufacturing could create issues since lower productivity is possible in usual operations. As Hurricane et al. (2024), critically stated that when a company’s basic work processes fail, it can no longer stand out in competition with others.
e) Recommendations for improvement should be made
On the basis of the above analysis, it is advised for Metro Manufacturing to include lean manufacturing as a crucial element of their overall work. Getting lean manufacturing into the company should lead to easier operations and enable the company to manage and follow both changes in costs and sales. As per the opinions of Palange and Dhatrak (2021), lean manufacturing techniques help a company move its products to the market quicker, which leads to greater demand for the products. As far as these changes in inflation and variable costs are concerned, they cannot be avoided, whereas Metro Manufacturing can handle them if they keep combining certain costs. When all the expenses are combined, it becomes easier to find and cut unnecessary costs, making sure the cost structure remains strong for many years ahead and allowing to track expenses and react fast to changes.
f) Summary
A better explanation of what was discussed above is that purchasing equipment offers only minor increases in sales and units at the start. Currently, the company is good at managing costs, which means serious long-term problems in operations are unlikely to happen. Since future rising costs are not sudden, Metro Manufacturing can use lean manufacturing methods to ensure their cost model remains steady.
Sincerely Yours,
Kabita Roy (CFO)
Metro Manufacturing
Task 3: Proposal for Setting up a System for Budgetary Control
Date: July 27, 2024
Arham Rahman, CEO
Metro Manufacturing,
Address: 4, universal square, Devonshire St N, Manchester M12 6JH, UK
Dear, Arham
a) Background and Cash Study Overview
The report highlights the budgeting issues faced by the company and also offers a clear plan to solve them. Medium-sized metal components intended for both the auto industry and construction are manufactured by the company. Managing finances with Excel is common among department heads, and they use flexible methods of budgeting that are rarely detailed or rigid. The items chosen for the budget are usually determined by what has been spent before, rather than by any specific strategy. A rise in costs of making products leads to a shortage in supply for metro and results in unsuccessful predictions, causing its debt to grow in the short run. The report discusses the key problems, suggests how the budget could be different, and presents a straightforward guide to budgeting.
b) Outlining the flaws of existing systems and giving suggestions for improvement in Budgetary Control
i) There is no single process that works for all when making a budget
Metro does not have just one way to set up a budget. As per critical views of Juhadi and Sofyan (2020), having good organisational systems and schedules in departments prevents different budgetary planning, which can be unclear and inconsistent.
Solution
Try to plan budgets for the year and each quarter at the set times. Use the same resources and ways to identify the commonalities among departments (Tabrizchi and Kuchaki Rafsanjani, 2020).
ii) Making a formal budget committee is not an option
Since budget issues are not controlled by one group, the decisions are modest and problems are allowed to persist.
Solution
Ensure the CFO, some department managers, and a finance employee are part of the budget committee. It is the committee’s job to make budget decisions and assure every member has the right and up-to-date information.
iii) Using Excel to take care of organising tasks
As the size of the data increases on a spreadsheet in Excel, the application can slow down and result in errors.
Solution
Using recent information and group work, one cloud tried accounting software or ERP options like SAP, Oracle, or QuickBooks (Fadoli, 2023).
iv) No methods exist for changing plans when issues come up
There are no features in Metro to compare actual and budgeted numbers. Hence, financial issues may be the first sign that these problems exist.
Solution
Every department should prepare monthly variance analysis reports that are then checked and approved by management. Choose the degree of change that is appropriate and ask if there are noticeable changes.
c) The Budgets and Additional Details
Metro can gain financial control through organising its activities with the use of several budget categories. These budgets are given below for use:
Labour Budget:
With a labour budget, one can estimate who will be needed and the expenses needed to achieve necessary production goals. HR methods are used to guide the management and cost monitoring of workers. Standard hours of work, wages and the amount to be produced are needed for forecasting. Important data is available through the HR or production management systems.
Sales Budget
A sales budget helps to predict the expected from all the items, customers, and areas. The marketing budget helps form budgets for producing purchasing and hiring because it predicts customer demand. The process of making a sales budget involves checking past performance, reviewing current market trends, figuring out the company’s sales goals and measuring client desire for products. The information is available in both sales and CRM software, yet a thorough market analysis must be conducted too (Shaikh, 2021).
Production Budget
The production needs are determined by how many products are required to achieve the expected sales figure. It guarantees that workers produce the right number of goods, steering clear of creating too many or insufficient amounts. A budget for this activity can be made by reviewing the sales budget, checking the inventory, estimating production, and confirming when delivery is supposed to happen. Summarised information comes from the sales, inventory, and the production team (Mollison, 2020).
Direct Material Budget
This budget identifies the supplies and their costs needed to complete the products. So, the company can function more efficiently and economically using what it truly requires. When a budget is formed, estimates of material costs and how much is to be produced are included. Documents associated with purchasing and making products are included in the pack (Shanawad, 2023).
Overhead Budget
Overhead budgets include expenses such as energy, tool or equipment replacements and costs from office administration. By properly monitoring fixed and variable overhead costs, a business gains more profitability. Look at past costs and organise each one as being fixed or variable. The company’s account information and department-specific reports are sources for the data.
Cash Budget
A cash budget outlines all planned money movements within a certain time to prevent problems with cash flow. Try not to get low on funds and rely on a smaller number of short-term loans. Creating a budget means anticipating income, figuring out required materials, staff, and debt expenses. Accounts receivable and receivable teams, or the finance department, may prepare the financial information needed (Barnhill and Rundio, 2021).
Capital Budget
A capital budget is used to manage planned investments in equipment, machinery or IT systems. It ensures portfolio investments provide the business with suitable rewards. Preparation involves exploring investment choices, weighing the benefits against the drawbacks, and figuring out the possible results. Project managers, engineers, and members of the finance team collaborate with those responsible for the construction budget (Bierman, 2020).
Master Budget
All the budgets for each department are merged into a master budget. The statement helps explain what the company’s future finances will be and plays a role in shaping the company’s business plans. Every department gives the finance group any data required for drawing up the master budget.
d) Methods of Using a Budgetary Control Process
A clear budget process allows Metro to include budgets into its usual financial practices. Ensure at the beginning that the targets are understood and add one person from each department to the planning process. As per critical views of Okafor and Odubade (2022), managers are advised to regularly check how the outcomes line up with what was listed in the budget, using variance analysis. Everyone using the same tool can update and keep tabs on information at the same moment. It is important for each manager to check the financial performance dashboard at least once each month. Teams work better together when everyone is open and straight to the point. Regular accounting checks and audits throughout Metro ensure good habits, help them respond fast when necessary, and keep them on lookout for new threats.
e) Recommendations
Metro should regularly check budget deviation, use software to help with budgeting, and allow various departments to take part in budget decisions. The group overseeing the budget should be chosen carefully. Work on coordination, accountability, and forecasting will lead to better decision-making and financial results.
f) Summary
Budgeting is an issue at Metro Manufacturing, due to their lack of step-by-step processes, reliable equipment, and teamwork. The report points out important considerations, establishes budgets for sales, production, and cash, and covers budget management. By using budget cycles, implementing integrated software, and regularly analysing differences, Metro can manage its activities better. Adhering to these guidelines can support good decisions, strong finances, and a steadily growing company.
References
- Asimakopulos, A., (2020). A Kaleckian theory of income distribution. In Investment, Employment and Income Distribution (pp. 23-46). Routledge.https://www.taylorfrancis.com/chapters/edit/10.4324/9780429033193-2/kaleckian-theory-income-distribution-asimakopulos
- Avi, M.S., (2021). The budget in hotel companies as a business management tool and as a means of empowering managers. INTERNATIONAL JOURNAL OF TOURISM AND HOTEL MANAGEMENT, 3(2 July-dec. 2021), pp.21-31.https://iris.unive.it/bitstream/10278/3741890/1/article%20avi%20hotel%20budget.pdf
- Barnhill, C. and Rundio, A., (2021). Developing a Cash Budget for the Savannah Squares. Case Studies in Sport Management, 10(1), pp.42-45.https://journals.humankinetics.com/view/journals/cssm/10/1/article-p42.xml
- Bierman, H., (2020). Capital budgeting. Handbook of financial planning and control, pp.77-89.https://www.taylorfrancis.com/chapters/edit/10.4324/9781003062165-7/capital-budgeting-harold-bierman
- Bimayu, D.A., (2023). Analisis Break Even Point (BEP) Dalam Menentukan Perencanaan Laba Perusahaan PT Sentra Food Indonesia 2021. SINOMIKA Journal: Publikasi Ilmiah Bidang Ekonomi Dan Akuntansi, 1(5), pp.1093-1104.https://www.publish.ojs-indonesia.com/index.php/SINOMIKA/article/view/583
- Buonanno, L. and Nugent, N., (2020). Policies and policy processes of the European Union. Bloomsbury Publishing.https://books.google.com/books?hl=en&lr=&id=shlHEAAAQBAJ&oi=fnd&pg=PR5&dq=Using+a+Budgetary+Control+Process&ots=dgpH8yjIDS&sig=4EFWk9qYS_hod8aP3s3jxtULZnU
- De Ridder, M., (2024). Market power and innovation in the intangible economy. American Economic Review, 114(1), pp.199-251.https://www.aeaweb.org/articles?id=10.1257%2Faer.20201079&s=09
- Dibiku, M.G., (2023). How salary and supervision affects Turnover intention through Job satisfaction the case of industrial zone located in Ethiopia. Journal of Human Resource Management, 26(1), pp.12-22.https://www.ceeol.com/search/article-detail?id=1166622
- Fadoli, A., (2023). Aplikasi Akuntansi Dalam Implementasi Manajemen Keuangan Pengusaha di Indonesia. AL-MIKRAJ Jurnal Studi Islam Dan Humaniora (E-ISSN 2745-4584), 4(1), pp.733-742.https://ejournal.insuriponorogo.ac.id/index.php/almikraj/article/view/4086
- Hirata, E., (2022). Shipping Digitalization. Supply Chain: Recent Advances and New Perspectives in the Industry 4.0 Era, p.107.https://books.google.com/books?hl=en&lr=&id=O8GFEAAAQBAJ&oi=fnd&pg=PA107&dq=Shipping&ots=K0X0Pi1itJ&sig=2J3BPp_T68jU9J6z1rtgAeVJQI4
- Hurricane, O.A., Callahan, D.A., Casey, D.T., Christopherson, A.R., Kritcher, A.L., Landen, O.L., Maclaren, S.A., Nora, R., Patel, P.K., Ralph, J. and Schlossberg, D., (2024). Energy principles of scientific breakeven in an inertial fusion experiment. Physical Review Letters, 132(6), p.065103. https://journals.aps.org/prl/abstract/10.1103/PhysRevLett.132.065103
- Jandaghian, Z. and Berardi, U., (2020). Analysis of the cooling effects of higher albedo surfaces during heat waves coupling the Weather Research and Forecasting model with building energy models. Energy and Buildings, 207, p.109627.https://www.sciencedirect.com/science/article/pii/S0378778819324156
- Juhadi, J. and Sofyan, Y., (2020). Pengaruh Sistem Pengendalian Internal Dan Audit Internal Terhadap Pelaksanaan Good Corporate Governance. Jemasi: Jurnal Ekonomi Manajemen Dan Akuntansi, 16(2), pp.17-32.https://scholar.archive.org/work/vhve4fn7fbcivnpm2pbzgnv35e/access/wayback/http://ejournal.iba.ac.id/index.php/jemasi/article/download/138/86
- Mollison, M., (2020). Budgeting. In Producing Videos (pp. 359-366). Routledge.https://www.taylorfrancis.com/chapters/edit/10.4324/9781003116844-22/budgeting-martha-mollison
- Okafor, I. and Odubade, O., (2022). FACTORS AFFECTING SCOPE CREEP IN PROJECT MANAGEMENT: IDENTIFY THE KEY FACTORS CONTRIBUTING TO SCOPE CREEP AND EXPLORE STRATEGIES TO PREVENT IT. International Journal of Engineering Technology and Management Sciences, 6(11), pp.10-5281. https://www.academia.edu/download/121888805/Mar_2022_14_1741971596_APRIL202221_1_.pdf
- Palange, A. and Dhatrak, P., (2021). Lean manufacturing a vital tool to enhance productivity in manufacturing. Materials Today: Proceedings, 46, pp.729-736.https://www.sciencedirect.com/science/article/pii/S2214785320398783
- Shaikh, J.M., (2021). The economic impact of budgeting amidst COVID-19 pandemic. In The 8th International Conference on New Ideas in Management, Economics and Business.https://www.academia.edu/download/122787106/16-224.pdf
- Shanawad, A., (2023). Cost Estimation, Budgeting and OEE Analysis for Binder Jetting at Sandvik Additive Manufacturing Division.https://www.diva-portal.org/smash/record.jsf?pid=diva2:1812502
- Slater, T., (2020). Rent control and housing justice. Finisterra, 55(114), pp.59-76.https://revistas.rcaap.pt/finisterra/article/view/19772
- Suzan, L., (2020). Effect of production Costs and Sales on the Company’s Net Profit. Jurnal Akuntansi, 24(2), pp.169-186.http://ecojoin.org/index.php/EJA/article/view/689
- Tabrizchi, H. and Kuchaki Rafsanjani, M., (2020). A survey on security challenges in cloud computing: issues, threats, and solutions. The journal of supercomputing, 76(12), pp.9493-9532.https://link.springer.com/article/10.1007/s11227-020-03213-1
- Thakur, V. and Mogha, A., (2022), May. IIOT in Utility Operations Paper. In ISUW 2021: Proceedings of the 7th International Conference and Exhibition on Smart Energy and Smart Mobility for Smart Cities (pp. 45-59). Singapore: Springer Nature Singapore.https://link.springer.com/chapter/10.1007/978-981-16-8727-3_5
- Vagner, I., (2020). Importance of break even point analysis. In Актуальные вопросы бухгалтерского учета, анализа и аудита в инновационной экономике (pp. 87-91).https://elibrary.ru/item.asp?id=44138212
Recently Downloaded Samples by Customers
Introduction to Principles Of Financial Planning Assignment Based on these financial concerns and objectives, I have provided...View and Download
Introduction to Human Engineering Assignment Help A flight accident is defined as a malfunction of the flight engine and a crash...View and Download
Introduction to Business Start-Up Module Assignment Sample Task 1 Edmundo Simulation Reflection 1A In the context of...View and Download
Introduction to Financial Analysis Of Toyota Motor Corporation Assignment Sample Toyota continued to be one of the top car...View and Download
Activity 1: Ethics Driven by Anger Witnessing the deforestation of large areas of rainforest Seeing deforestation by a...View and Download
People Management Assignment on HR Strategies at Morrison's Enhance your knowledge of effective people management...View and Download